
Turn abandoned patents
into your own filing
into your own filing
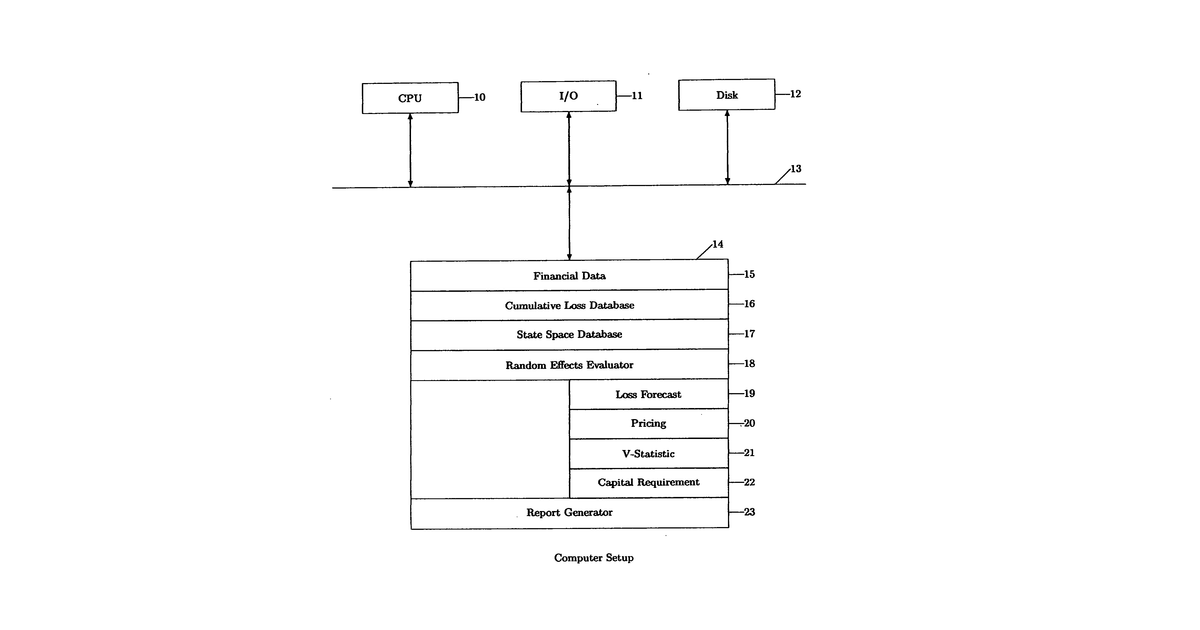
This invention describes a computer-based method for predicting financial losses in loan portfolios. It works by taking historical loan data, including borrower and account details, and segmenting it into groups. Then, it models how losses accumulate over time using S-shaped curves and advanced statistical techniques, specifically a hierarchical Bayesian model. This allows it to estimate total dollar losses and their variability, which can be used for managing risk, valuing financial products, and setting capital requirements.
Why it matters: Filed before the widespread availability of cloud computing and advanced machine learning libraries, which now make the complex statistical modeling and data processing described far more accessible and efficient. Increased regulatory demands for robust risk modeling since 2006 also make such a system more relevant.
AI gives you a few directions you could take this. Pick one, and we check whether your version is different enough to patent, then write the filing.
Reinvent this with AI


